Equinox Partners, L.P. - Q3 2026 Letter
Dear Partners and Friends,
PERFORMANCE
Equinox Partners, L.P. rose +21.2% net of fees in the third quarter and is up +40.3% year to date. By comparison, the S&P 500 index appreciated +2.3% in the quarter and is up +12.7% for the year to date.
Equinox’s strong performance in the quarter was driven by the appreciation of our precious metal mining equities as well as our energy-related investments. Our top mining holding, Solidcore Resources, rallied over 60% in the quarter, contributing to the outperformance of our gold mining equities relative to the broader industry averages. It is notable that these gains in the mining equities occurred during a quarter in which the spot gold price only rose a modest +2.8%. In the energy portfolio, the spot WTI oil price rose nearly 29% from $70 to $90 per barrel, yet our oil and gas stocks rose just +17% as markets continue to see high oil prices as a temporary phenomenon.
We remain high-conviction gold mining investors given our federal government's failure to control spending. In the letter that follows, we will discuss the politics of America's ballooning debt, review two recent exits from our energy sector investments, and provide a post-election update on Brazil.
The Changing Politics of America's Government Debt
“How did you go bankrupt?”
“Two ways. Gradually, then suddenly.”
Ernest Hemingway, The Sun Also Rises
America’s federal government is in the gradual phase of bankruptcy. Our fiscal path is unsustainable, but it remains unclear when we will be forced to change. The Japanese ran their government debt-to-GDP ratio over 200% without a crisis. So, with America’s federal debt-to-GDP at a mere 123%, our politicians continue to spend as if deficits don't matter.
Conventional wisdom on Wall Street holds that the Treasury market will dictate the timing of the ultimate solution. When the federal government can't roll over its debt on acceptable terms, politicians will act. But, even when that moment arrives, the crisis will be manageable. The Treasury and Federal Reserve will both buy Treasury bonds to maintain order in capital markets while politicians work out a solution.
We are less sanguine about the contours of America’s debt endgame. The current turmoil in France is a reminder of just how toxic the combination of over-indebtedness, social unrest and a presidential election cycle can be. There are an uncomfortable number of similarities between the current situation in France and America. Like France, America is socially and politically divided. Like France, cost-of-living increases are the top political issue in the U.S. And, like France, America has an upcoming presidential election which could usher in meaningful policy change.
In France, the twilight of Macron’s 10-year presidency prompted serious political proposals. Marine Le Pen, currently leading the polls with 35% of first-round votes, has proposed reducing government spending by €140 billion cumulatively over the next six years. And, her most plausible challenger, Jean-Luc Mélenchon, has proposed simply writing off the French debt held by the French Central Bank.
America’s presidential election cycle begins next Wednesday, promptly after the November midterms. We expect Americans aspiring to the presidency will also float a variety of serious fiscal proposals. The ideas will likely include everything from a wealth tax to means-testing Social Security. At this moment, it’s not the specifics of the proposals that matter as no one credible is likely to propose radical spending cuts. Rather, it is the political appetite to do something, a calculation that stands in stark contrast to the political wisdom in America’s last three presidential election cycles.
In 2016, with America’s national debt-to-GDP at just 105% ($20 trillion at the time), our debt crisis didn’t yet appear politically ripe for solving. In 2020, the COVID crisis and related emergency spending drowned out any discussion about America's unsustainable fiscal path. And, most recently, in the 2024 election, Trump was able to dismiss out of hand questions about the fiscal deficit, while Joe Biden and Kamala Harris were forced to focus on their competence to serve as president. As such, America has gone through ten long years without serious discussion about our fiscal situation. America's 2028 political cycle will likely prove a turning point in this regard, just as the 2027 election is proving to be a turning point for France.
As our 2028 cycle heats up, markets will likely conclude that something is going to happen and will begin to discount the looming policy shock. It is also likely, in our opinion, that a Democratic-controlled Congress, in cooperation with a lame-duck President Trump, will take a stab at America’s fiscal problem preemptively. Trump is not one to punt on hard decisions, and his Treasury Secretary Scott Bessent is on the record stating that he took the job because he wants to participate in a global economic reordering. He may soon get the chance.
Gran Tierra Energy Sale
We invested in Gran Tierra Energy in June 2024 following the company’s exploration success in Ecuador. Immediately following our investment, Gran Tierra acquired i3 Energy in Canada. The transaction, which didn’t make financial or strategic sense, caused Gran Tierra’s stock to decline by over 40%. At Gran Tierra’s newly discounted share price, we decided to increase our ownership of and influence over the company. We ultimately bought 18% of the company and decided to join the board with the intention of improving Gran Tierra’s capital allocation decisions. Sensing the likely result of our decision, Gran Tierra’s board preemptively undertook a strategic review of its portfolio. That review resulted in a decision to sell the company’s Latin American business to surface value. That transaction, announced in early August of this year, enabled us to sell our position at an attractive price.
Decision to Exit Seplat Energy
We first started purchasing shares of Seplat Energy in March 2022. When the company bought Exxon out of Nigeria, we substantially increased our position. We always viewed Seplat as the best run Nigerian oil company. The company’s breakeven production costs were so low that Seplat was able to keep paying its dividend throughout 2020 when the Brent Crude oil price averaged $43 per barrel, including through the depths of the COVID-induced oil crash. And because of the Exxon deal, Seplat was able to more than double the business without raising equity. Despite these attractive attributes, Seplat traded at a substantial discount to international peers due to the poor reputation of its home country. Prior to 2026, the stock traded at a 20-30% free cash flow (FCF) yield and paid a high single-digit dividend yield, while also investing to grow production.
We particularly liked Seplat’s shareholding structure. At the time of our investment, the company had a variety of unaffiliated shareholders, each with their own board representation. The French oil company Maurel et Prom owned 20% of Seplat; the two co-founders each owned stakes ranging from 6% to 12%; another 15% was owned by the South African asset managers Allan Gray and Sustainable Capital; and 14% of the company was owned by Monaco-based investor Samuel Dossou. In short, there was no single owner powerful enough to take advantage of minority investors and impair our investment.
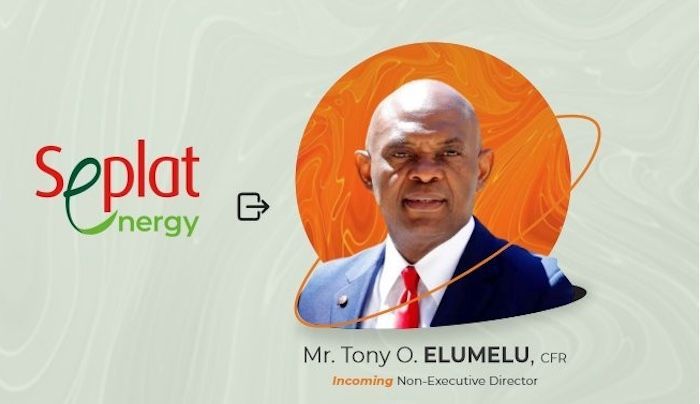
Early this year, the distributed ownership structure of Seplat ended abruptly. Tony Elumelu, a Nigerian billionaire, acquired Maurel et Prom’s 20% stake and was appointed to Seplat’s board. Shortly thereafter, the two South African asset managers sold their shares as well. Tony was the rumored buyer of their shares. While it was impossible for us to verify these rumors, it became clear to us that Tony had complete control over the company.
We viewed Tony’s control with skepticism, but his purchase was viewed very favorably by local Nigerian investors. The local view was that finally Seplat has a ‘Big Man’ in charge who has the ear of the ‘Big Men’ in Abuja and can get things done. While there is probably truth to this, Tony’s corporate governance track record made us uncomfortable with his level of control.
Once in control, Tony removed Roger Brown, Seplat’s foreign CEO whom we greatly respected, and installed a local Nigerian in his place. Tony also made himself the Chairman of Seplat’s board. Again, to our surprise, the market applauded these moves and the stock rallied further. We sold half our position on the day of the CEO change announcement and then met with both the new CEO and Tony himself to dig deeper into the new governance structure. After both meetings, and a subsequent further increase in the share price, we exited the position completely. We sold the last of our shares at a 10% FCF yield on our forward-year forecast, or a mid-teens FCF yield 3-5 years out. After we sold, the stock rallied another 15% and now trades at an estimated 8% FCF yield on forward estimates, and a low-teens FCF yield 3-5 years out.
Seplat was a very successful investment for us. From when we purchased it to today, annual production and cash flow have more than tripled. Our Seplat investment returned approximately 250% prior to Tony's involvement, and more than doubled again in the short time after he bought in. In total, the position returned over 700% across our four-and-a-half-year holding period. Some part of this was good stock picking, and some part was luck.
Brazil's Election
Brazil’s election delivered a series of surprises: Flavio's first-round victory, Lula’s second-round victory, Justice Moraes' attempt to confiscate Flavio's passport, and Flavio's decision to relocate to the United States.
With Lula still in power, we expect the Brazilian real will weaken as Lula forces policy rates lower without the necessary fiscal adjustment. This scenario will present a challenging macroeconomic backdrop for our companies but is not all bad news. In an environment of scarce capital, our well-capitalized portfolio companies will likely consolidate their sector leadership positions. Several of our Brazilian portfolio companies stand to benefit from softening competition from private equity.
In the post-election sell-off, we added to our Brazilian currency hedge and our position in Grupo GPS. Grupo GPS is the leading business services outsourcing company in Brazil, and we recently profiled this relatively new investment as a case study of our process. If you haven’t already, we encourage you to watch our case study webinar (access the replay via the following link: Grupo GPS Case Study - Oct 2026 - Video Replay).
Organizational Update
In September, we added Will Robinson to our investment team. He joins us from Sixth Street Partners, where he was an associate on their Infrastructure investment team. Will originally hails from Texas, outside of Dallas, and received a B.B.A. in Finance from The University of Texas at Austin. We are excited for him to bolster the analytical horsepower of our mining research.
Sincerely,
Equinox Partners Investment Management
[1] Please note that estimated performance has yet to be audited and is subject to revision. Performance figures constitute confidential information and must not be disclosed to third parties. An investor’s performance may differ based on timing of contributions, withdrawals and participation in new issues.
Unless otherwise noted, all company-specific data derived from internal analysis, company presentations, Bloomberg, FactSet or independent sources. Values as of 9.30.26, unless otherwise noted.
This document is not an offer to sell or the solicitation of an offer to buy interests in any product and is being provided for informational purposes only and should not be relied upon as legal, tax or investment advice. An offering of interests will be made only by means of a confidential private offering memorandum and only to qualified investors in jurisdictions where permitted by law.
An investment is speculative and involves a high degree of risk. There is no secondary market for the investor’s interests and none is expected to develop and there may be restrictions on transferring interests. The Investment Advisor has total trading authority. Performance results are net of fees and expenses and reflect the reinvestment of dividends, interest and other earnings.
Prior performance is not necessarily indicative of future results. Any investment in a fund involves the risk of loss. Performance can be volatile and an investor could lose all or a substantial portion of his or her investment.
The information presented herein is current only as of the particular dates specified for such information and is subject to change in future periods without notice.