Equinox Partners, L.P. - Q3 2011 Letter

Dear Partners and Friends,

PERFORMANCE & PORTFOLIO

Equinox Partners fell -18.9% in the quarter ended September 30, 2011. In October, the fund was up +11.0%. In November we estimate the fund was down -2.8%, bringing our year-to-date return to -21.3%.

Downgrade!


“… [T]he downgrade reflects our view that the effectiveness, stability and predictability of American policymaking and political institutions have weakened at a time of ongoing fiscal and economic challenges… The outlook on the long-term rating is negative.” 

           —S&P announcement of US debt downgrade August 5, 2011


With these fateful words, Standard & Poor’s Corporation announced the fall of the world’s reserve currency from “risk-free” grace. Thus, America joins a growing list of developed countries whose government balance sheets are being called into question. A recent Bank for International Settlement working paper sums up the well known reasons for the rash of developed country downgrades:


“Since the start of the financial crisis, industrial country public debt levels have increased dramatically. And they are set to continue rising for the foreseeable future. A number of countries face the prospect of large and rising future costs related to the ageing of their population… Our projections of public debt ratios lead us to conclude that the path pursued by fiscal authorities in a number of industrial countries is unsustainable.”[1] 


If history is any guide, so long as financing costs of government debt remain low, any effort to rouse the requisite political will to reverse the process will fail. This outcome is unfortunate for America and Japan because these countries’ low-cost financing contradicts potential proximity of a sovereign debt crisis. In quick succession, investors’ concern about their credit quality could translate into higher interest rates and those higher rates would in turn exacerbate the very problem investors are worried about by increasing government interest expenses.                                                                                                 

America and Japan continue to benefit from a major, and we believe temporary, distinction that bond investors are making between financially-stretched nations with government printing presses and those without. Those with printing presses have seen their interest rates stay low or even decline as worried investors flee countries that lack a printing press. But, while central bank printing may be able to prevent a bad bond auction, it is no panacea. After all, the newly printed money is highly inflationary and in the medium term at least as bond bearish as a failed auction. Accordingly, Equinox’s short sovereign debt position remains largely focused on countries with a central bank, specifically U.S. and Japan. Because it is our largest and, we believe, the most compelling short, we will focus on the Japanese fiscal/credit situation in this letter (please also see our Q3 2009 and Q2 2003 letters on this topic).

Equinox’s Sovereign Debt Shorts

Equinox has had a long and usually profitable legacy of recognizing large-scale global financial imbalances. Our long-running, large precious metals exposure, our preference for emerging markets, and our shorting various companies involved in the U.S. housing bubble are examples of successful themes. Our short of the late 1990s tech bubble is an unsuccessful example. 


In recent years we have ramped-up the Japanese Government Bond (JGB) short—a position we initiated in 2003. As of November 30, the position is 32% of partners’ capital.[2] Our investment rationale is as compelling as it is simple: As bond yields collapsed in the aftermath of the 2008 Credit Crisis, and government deficits exploded, the asymmetry of risk and reward with this short became extremely positive. While we have been early, it is our judgment that we dare not miss such a lopsidedly attractive investment opportunity.


“A Bug in Search of a Windshield,” is the colorful metaphor that John Mauldin and Jonathan Tepper use to describe the credit condition of Japanese Government Bonds. With over 200% government gross debt/GDP, developed over their 20 years of Keynesian spending to compensate for economic weakness, and government spending still more than double tax receipts, Japan is by far and away the most indebted sovereign.  Ironically, Japan also has the lowest interest rates in the developed world in the face of massive fiscal deficits. This combination makes JGBs a particularly compelling short. 


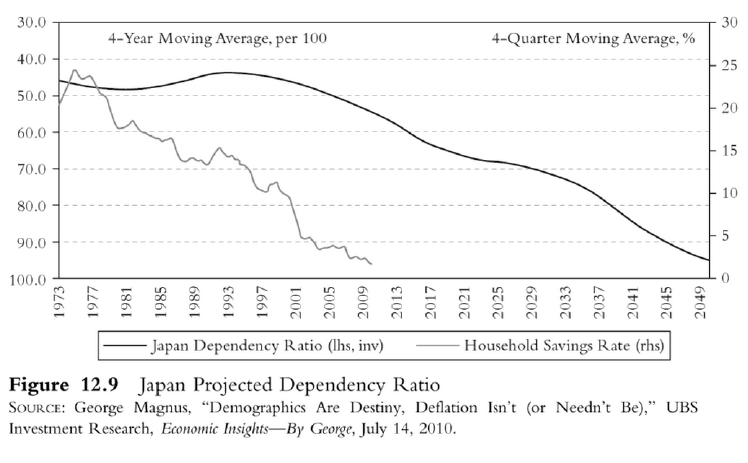
In addition to their very high price, there are two particularly attractive aspects of shorting JGBs. The first is the reflexivity referenced above. As Kyle Bass—a fellow JGB short seller—points out, a mere 2 percent increase in the extremely low JGB interest rates, would mean that, “their debt service alone could easily exceed their entire central government revenue—checkmate.”[3] Additionally, Japan’s previously abundant source of cash inflows is drying up rapidly. The high savings rate of its population that was a hallmark of Japan’s development is collapsing as the aging population retires (graph below).[4] Given the asymmetric nature of this investment—and choosing two scenarios we feel have similar probabilities—if the JGB yield curve were to drop -0.5% across the curve we would stand to lose -$50m while if the curve increased +5.0% we would make +$167m.[5]  And with the low annual carry cost of about 0.4% of partners’ capital, we have time to wait.
Mea Culpa: Healthcare Locums

The business of identifying and placing people looking for work requires industry expertise and a good network, but needs little capital. Consequently, these businesses tend to generate high returns on capital and attract our interest.  In September 2008, we had our first meeting with Healthcare Locums (HCL), a temp staffing company based in London. HCL was particularly interesting because it focused exclusively on healthcare professionals, and it was cheap.


As we continued our work during the ensuing weeks, we were encouraged by what we learned. Although only founded in 2003, HCL had become the UK’s market leader in providing temporary doctors, allied health professionals and social workers, building the business both through organic growth and a number of bolt-on acquisitions. We found HCL’s market strategy particularly compelling: focusing on staffing specialists in harder-to-fill positions. As a result, they were able to earn a higher margin while also being able to pay their locums more. Because of their dominance in the harder-to-find specialties, HCL could fill jobs that other firms could not; consequently, they were able to charge more. This dynamic created a network effect for their business. 


In addition to this domestic business, HCL was expanding into permanent placement of healthcare professionals outside the United Kingdom. By using the same recruiting network as the existing domestic business, the margins on the international business would be significantly higher than the temporary placement business. While this expansion was still developing, HCL had already won a large contract with Emaar Healthcare that sell-side analysts estimated to be worth 38 pence per share, on a stock trading at around 120 pence. Even without this international business as a significant contributor to earnings, the stock traded at a P/E of 9.6x 2008 and 5.8x 2009 consensus earnings.


Our enthusiasm for Healthcare Locums was tempered by two restatements of earnings related to capitalization of expenses by the CEO’s previous business a decade earlier. But, HCL had just hired two new senior executives, one as Executive Chief Operating Officer and one as Executive Finance Director, with lots of industry experience and untarnished resumes. Given the purported fundamentals, combined with our historic success with such businesses and the length of time that had transpired since the former incident, we decided to give HCL’s management the benefit of the doubt.


Our reservations about management were hastily confirmed in early 2011, when the board of directors suspended trading in Healthcare Locums’ stock shortly after consummating a major acquisition of an Australian Healthcare business. As the board was looking over the end-of-year results, it became clear to them that the management had made false representations about the state of the business. On January 25, 2011, concurrent with the suspension, the board announced the following: “Serious accounting irregularities have been brought to the attention of the Board as a result of which the Company will be carrying out an immediate investigation to consider the financial implications. The Company also announces that both Executive Vice Chairman, Kate Bleasdale, and Chief Financial Officer, Diane Jarvis have been suspended pending the outcome of the investigation.”


During the suspension, which lasted until September 13, HCL replaced its entire board and management. After completing a lengthy investigation, the new executive team found that the company had not only capitalized expenses they should have expensed, but had also recognized fictitious revenues in the previous three years. 


As a result of the investigation, the board concluded that the remaining business simply could not handle the amount of debt that the company owed. In response, the new board was forced to do a large equity raise at 10 pence per share, some 90% below the last traded price. The dilutive equity raise virtually wiped out existing shareholders. 


The mistake of investing in HCL cost us about 2.9% of capital this year and reinforced a lesson that we long ago learned: the best predictor of future behavior is past behavior. In this case, we were attracted by the investment opportunity and made the mistake of giving less credence to one of our fundamental investment tenets. Our experience with Healthcare Locums was a painful reminder that we should only invest with the most principled managers.


Sincerely,


Sean Fieler                   

Daniel Gittes

William W. Strong                     


END NOTES

[1] Stephen G. Cecchetti, MS Mohanty, Fabrizio Zampolli, “The Future of Public Debt: Prospects and Implications,” Abstract of BIS Working Paper No. 300, March 2010.


[2] Stated percentage is the notional amount of JGB swaps as a percentage of partners’ capital.


[3] Hayman Capital Management, L.P. Investor Letter, “The Cognitive Dissonance of It All”, February 14, 2011.


[4] Dependency ratio shows the number of non-workers per 100 workers.


[5] This does not factor in possible Yen currency devaluation which would likely offset some of the gains or losses. 
By Kieran Brennan • November 3, 2026
Sean Fieler and Equinox Partners Profiled in OWL October 2026 Edition
By Kieran Brennan • November 3, 2026
Dear Partners and Friends, PERFORMANCE The Equinox Partners Precious Metals Fund rose +19.6% in the third quarter and is up +21.1% for the year to date. By comparison, in the third quarter, the price of gold ticked up +2.8% and the MVIS Junior Gold Mining Index rallied +16.8%, finishing the year to date through Q3 down -3.8% and up 0.3% respectively. Performance for the quarter was driven by our producing miner portfolio, and most notably our largest holding, Solidcore Resources, which rose +60%. In September, Solidcore announced a tender offer to buy back over 23% of its shares outstanding, and in early October the company confirmed the entire offer had been tendered. Other notable sources of outperformance in the quarter were our investments in producers such as B2Gold, DPM Metals, and Discovery Mining. The exploration-stage segment of the portfolio rallied +10%, lagging the move in the MVIS Junior Gold Mining Index. Portfolio Activity In the third quarter, we initiated three new pre-production positions and added to five of our existing portfolio companies. We fully exited two portfolio companies, including Omai Gold Mines, at a substantial profit. We also continued to trim two of our West African producing gold miners. In mid-2024, our Africa exposure was over 40% portfolio weight. Today our exposure to Africa is less than 15%. This reduction has been offset by our increasing exposure to companies in Kazakhstan and Canada. Site Visits The mining research team has been traveling extensively in recent months. We have conducted mine site visits to portfolio company projects in Papua New Guinea (K92 & New Pacific), Kazakhstan (Solidcore, Arres & Pallas), Northern Territories of Canada (B2Gold). We also attended a series of mining conferences in Colorado where we spent time with the management teams and directors of several of our investments. We remain high-conviction gold mining investors given our federal government's failure to control spending. In the letter that follows, we will discuss the politics of America's ballooning debt. The Changing Politics of America's Government Debt “How did you go bankrupt?” “Two ways. Gradually, then suddenly.” Ernest Hemingway, The Sun Also Rises America’s federal government is in the gradual phase of bankruptcy. Our fiscal path is unsustainable, but it remains unclear when we will be forced to change. The Japanese ran their government debt-to-GDP ratio over 200% without a crisis. So, with America’s federal debt-to-GDP at a mere 123%, our politicians continue to spend as if deficits don't matter. Conventional wisdom on Wall Street holds that the Treasury market will dictate the timing of the ultimate solution. When the federal government can't roll over its debt on acceptable terms, politicians will act. But, even when that moment arrives, the crisis will be manageable. The Treasury and Federal Reserve will both buy Treasury bonds to maintain order in capital markets while politicians work out a solution. We are less sanguine about the contours of America’s debt endgame. The current turmoil in France is a reminder of just how toxic the combination of over-indebtedness, social unrest and a presidential election cycle can be. There are an uncomfortable number of similarities between the current situation in France and America. Like France, America is socially and politically divided. Like France, cost-of-living increases are the top political issue in the U.S. And, like France, America has an upcoming presidential election which could usher in meaningful policy change. In France, the twilight of Macron’s 10-year presidency prompted serious political proposals. Marine Le Pen, currently leading the polls with 35% of first-round votes, has proposed reducing government spending by €140 billion cumulatively over the next six years. And, her most plausible challenger, Jean-Luc Mélenchon, has proposed simply writing off the French debt held by the French Central Bank. America’s presidential election cycle begins next Wednesday, promptly after the November midterms. We expect Americans aspiring to the presidency will also float a variety of serious fiscal proposals. The ideas will likely include everything from a wealth tax to means-testing Social Security. At this moment, it’s not the specifics of the proposals that matter as no one credible is likely to propose radical spending cuts. Rather, it is the political appetite to do something, a calculation that stands in stark contrast to the political wisdom in America’s last three presidential election cycles. In 2016, with America’s national debt-to-GDP at just 105% ($20 trillion at the time), our debt crisis didn’t yet appear politically ripe for solving. In 2020, the COVID crisis and related emergency spending drowned out any discussion about America's unsustainable fiscal path. And, most recently, in the 2024 election, Trump was able to dismiss out of hand questions about the fiscal deficit, while Joe Biden and Kamala Harris were forced to focus on their competence to serve as president. As such, America has gone through ten long years without serious discussion about our fiscal situation. America's 2028 political cycle will likely prove a turning point in this regard, just as the 2027 election is proving to be a turning point for France. As our 2028 cycle heats up, markets will likely conclude that something is going to happen and will begin to discount the looming policy shock. It is also likely, in our opinion, that a Democratic-controlled Congress, in cooperation with a lame-duck President Trump, will take a stab at America’s fiscal problem preemptively. Trump is not one to punt on hard decisions, and his Treasury Secretary Scott Bessent is on the record stating that he took the job because he wants to participate in a global economic reordering. He may soon get the chance. Organizational Update In September, we added Will Robinson to our investment team. He joins us from Sixth Street Partners, where he was an associate on their Infrastructure investment team. Will originally hails from Texas, outside of Dallas, and received a B.B.A. in Finance from The University of Texas at Austin. We are excited for him to bolster the analytical horsepower of our mining research.
By Kieran Brennan • November 2, 2026
Sean Fieler Interviews Judy Shelton at Monetary Forum in D.c. 2026 "A Conversation on Monetary Governance and Federal Reserve Oversight"
By Kieran Brennan • October 30, 2026
Dear Partners and Friends, PERFORMANCE Kuroto Fund, L.P. was up +8.6%, net of all fees, in the third quarter of 2026, and is up +43.4% for the year-to-date. By comparison, the MSCI Emerging Markets Index declined -0.4% in the quarter and is now up +23.4% for the year-to-date. The MSCI Frontier Markets Index declined -0.3% in the third quarter and is up +9.8% year-to-date. Performance in the third quarter was led by an exceptionally strong quarter for shares in our Kazakh gold miner, Solidcore Resources, followed by over +20% moves in both our energy equities and our financials holdings in Georgia and Kazakhstan. In the letter to follow, we provide an update on Kuroto’s energy portfolio in light of the strong year-to-date returns and discuss our decisions to sell energy investments Gran Tierra Energy and Seplat Energy. Lastly, we share our updated outlook for Brazil post-election. Oil Portfolio Update Coming into 2026, the oil and gas equities in Kuroto had a 22% aggregate portfolio weighting. Collectively, that portfolio has appreciated +89%, contributing over one-third of the fund’s gross performance for the year. Since then, we have reduced our exposure to the sector, with oil and gas equities now making up 15% of the fund. We exited our investment in Seplat Energy and have nearly completed the exit of our holding in Gran Tierra Energy. These oil and gas equities appreciated in part because of the oil price spike induced by the Iran conflict, as well as for idiosyncratic, company-specific reasons. As we analyze our three remaining oil and gas positions, we believe they are attractively valued and should also provide the portfolio with a partial hedge should oil prices rise further due to the deterioration of the conflict in the Middle East. With the capital raised via sales of energy equities, we reallocated into attractively priced investments in Brazil, such as Grupo GPS, as well as into new positions in countries that have been negatively affected by the high oil prices from the Iran conflict, namely Bangladesh and Egypt. Gran Tierra Energy Sale We initiated our holding in Gran Tierra Energy in Kuroto in July 2025. The company had traded off significantly when it followed up its 2024 exploration success in Ecuador with the ill-advised acquisition of i3 Energy in Canada. The transaction, which didn’t make financial or strategic sense, caused Gran Tierra’s stock to decline by over 40%. At the discounted share price, we decided to build our position and influence over the company. We ultimately bought 18% of the company and decided to join the board with the intention of improving Gran Tierra’s capital allocation decisions. Sensing the likely result of our decision, Gran Tierra’s board preemptively undertook a strategic review of its portfolio. That review resulted in a decision to sell the company’s Latin American business to surface value. That transaction, announced in early August of this year, enabled us to begin selling our position at attractive prices. Decision to Exit Seplat Energy We first started purchasing shares of Seplat in Kuroto in December 2021. When the company bought Exxon out of Nigeria, we substantially increased our position. We always viewed Seplat as the best run Nigerian oil company. The company’s breakeven production costs were so low that Seplat was able to keep paying its dividend throughout 2020 when the Brent Crude oil price averaged $43 per barrel, including through the depths of the COVID-induced oil crash. And because of the Exxon deal, Seplat was able to more than double the business without raising equity. Despite these attractive attributes, Seplat traded at a substantial discount to international peers due to the poor reputation of its home country. Prior to 2026, the stock traded at a 20-30% free cash flow (FCF) yield and paid a high single-digit dividend yield, while also investing to grow production. We particularly liked Seplat’s shareholding structure. At the time of our investment, the company had a variety of unaffiliated shareholders, each with their own board representation. The French oil company Maurel et Prom owned 20% of Seplat; the two co-founders each owned stakes ranging from 6% to 12%; another 15% was owned by the South African asset managers Allan Gray and Sustainable Capital; and 14% of the company was owned by Monaco-based investor Samuel Dossou. In short, there was no single owner powerful enough to take advantage of minority investors and impair our investment. Early this year, the distributed ownership structure of Seplat ended abruptly. Tony Elumelu, a Nigerian billionaire, acquired Maurel et Prom’s 20% stake and was appointed to Seplat’s board. Shortly thereafter, the two South African asset managers sold their shares as well. Tony was the rumored buyer of their shares. While it was impossible for us to verify these rumors, it became clear to us that Tony had complete control over the company. We viewed Tony’s control with skepticism, but his purchase was viewed very favorably by local Nigerian investors. The local view was that finally Seplat has a ‘Big Man’ in charge who has the ear of the ‘Big Men’ in Abuja and can get things done. While there is probably truth to this, Tony’s corporate governance track record made us uncomfortable with his level of control. Once in control, Tony removed Roger Brown, Seplat’s foreign CEO whom we greatly respected, and installed a local Nigerian in his place. Tony also made himself the Chairman of Seplat’s board. Again, to our surprise, the market applauded these moves and the stock rallied further. We sold half our position on the day of the CEO change announcement and then met with both the new CEO and Tony himself to dig deeper into the new governance structure. After both meetings, and a subsequent further increase in the share price, we exited the position completely. We sold the last of our shares at a 10% FCF yield on our forward-year forecast, or a mid-teens FCF yield 3-5 years out. After we sold, the stock rallied another 15% and now trades at an estimated 8% FCF yield on forward estimates, and a low-teens FCF yield 3-5 years out. Seplat was a very successful investment for us. From when we purchased it to today, annual production and cash flow have more than tripled. Our Seplat investment returned over 700% prior to Tony's involvement, and has nearly doubled again in the short time since he bought in. In total, our initial holding in Kuroto returned over 1,000% across our nearly five-year investment. Some of this was good stock picking, and some was luck. Brazil's Election Brazil’s election delivered a series of surprises: Flavio's first-round victory, Lula’s second-round victory, Justice Moraes' attempt to confiscate Flavio's passport, and Flavio's decision to relocate to the United States. With Lula still in power, we expect the Brazilian real will weaken as Lula forces policy rates lower without the necessary fiscal adjustment. This scenario will present a challenging macroeconomic backdrop for our companies but is not all bad news. In an environment of scarce capital, our well-capitalized portfolio companies will likely consolidate their sector leadership positions. Several of our Brazilian portfolio companies stand to benefit from softening competition from private equity. One of our investments that should benefit from an environment with a higher cost of capital in Brazil is Grupo GPS, the country's leading business services outsourcing company. A key part of the investment thesis is that GPS will continue to make high-return acquisitions, and a lower valuation environment should help. We recently profiled Grupo GPS as an example of our investment process. If you haven’t already, we encourage you to watch our case study webinar (access the replay via the following link: Grupo GPS Case Study - Oct 2026 - Video Replay ). Organizational Update In September, we added Will Robinson to our investment team. He joins us from Sixth Street Partners, where he was an associate on their Infrastructure investment team. Will originally hails from Texas, outside of Dallas, and received a B.B.A. in Finance from The University of Texas at Austin. We are excited for him to bolster the analytical horsepower of our mining research.
By Kieran Brennan • October 29, 2026
Dear Partners and Friends, PERFORMANCE Equinox Partners, L.P. rose +21.2% net of fees in the third quarter and is up +40.3% year to date. By comparison, the S&P 500 index appreciated +2.3% in the quarter and is up +12.7% for the year to date. Equinox’s strong performance in the quarter was driven by the appreciation of our precious metal mining equities as well as our energy-related investments. Our top mining holding, Solidcore Resources, rallied over 60% in the quarter, contributing to the outperformance of our gold mining equities relative to the broader industry averages. It is notable that these gains in the mining equities occurred during a quarter in which the spot gold price only rose a modest +2.8%. In the energy portfolio, the spot WTI oil price rose nearly 29% from $70 to $90 per barrel, yet our oil and gas stocks rose just +17% as markets continue to see high oil prices as a temporary phenomenon. We remain high-conviction gold mining investors given our federal government's failure to control spending. In the letter that follows, we will discuss the politics of America's ballooning debt, review two recent exits from our energy sector investments, and provide a post-election update on Brazil. The Changing Politics of America's Government Debt “How did you go bankrupt?” “Two ways. Gradually, then suddenly.” Ernest Hemingway, The Sun Also Rises America’s federal government is in the gradual phase of bankruptcy. Our fiscal path is unsustainable, but it remains unclear when we will be forced to change. The Japanese ran their government debt-to-GDP ratio over 200% without a crisis. So, with America’s federal debt-to-GDP at a mere 123%, our politicians continue to spend as if deficits don't matter. Conventional wisdom on Wall Street holds that the Treasury market will dictate the timing of the ultimate solution. When the federal government can't roll over its debt on acceptable terms, politicians will act. But, even when that moment arrives, the crisis will be manageable. The Treasury and Federal Reserve will both buy Treasury bonds to maintain order in capital markets while politicians work out a solution. We are less sanguine about the contours of America’s debt endgame. The current turmoil in France is a reminder of just how toxic the combination of over-indebtedness, social unrest and a presidential election cycle can be. There are an uncomfortable number of similarities between the current situation in France and America. Like France, America is socially and politically divided. Like France, cost-of-living increases are the top political issue in the U.S. And, like France, America has an upcoming presidential election which could usher in meaningful policy change. In France, the twilight of Macron’s 10-year presidency prompted serious political proposals. Marine Le Pen, currently leading the polls with 35% of first-round votes, has proposed reducing government spending by €140 billion cumulatively over the next six years. And, her most plausible challenger, Jean-Luc Mélenchon, has proposed simply writing off the French debt held by the French Central Bank. America’s presidential election cycle begins next Wednesday, promptly after the November midterms. We expect Americans aspiring to the presidency will also float a variety of serious fiscal proposals. The ideas will likely include everything from a wealth tax to means-testing Social Security. At this moment, it’s not the specifics of the proposals that matter as no one credible is likely to propose radical spending cuts. Rather, it is the political appetite to do something, a calculation that stands in stark contrast to the political wisdom in America’s last three presidential election cycles. In 2016, with America’s national debt-to-GDP at just 105% ($20 trillion at the time), our debt crisis didn’t yet appear politically ripe for solving. In 2020, the COVID crisis and related emergency spending drowned out any discussion about America's unsustainable fiscal path. And, most recently, in the 2024 election, Trump was able to dismiss out of hand questions about the fiscal deficit, while Joe Biden and Kamala Harris were forced to focus on their competence to serve as president. As such, America has gone through ten long years without serious discussion about our fiscal situation. America's 2028 political cycle will likely prove a turning point in this regard, just as the 2027 election is proving to be a turning point for France. As our 2028 cycle heats up, markets will likely conclude that something is going to happen and will begin to discount the looming policy shock. It is also likely, in our opinion, that a Democratic-controlled Congress, in cooperation with a lame-duck President Trump, will take a stab at America’s fiscal problem preemptively. Trump is not one to punt on hard decisions, and his Treasury Secretary Scott Bessent is on the record stating that he took the job because he wants to participate in a global economic reordering. He may soon get the chance. Gran Tierra Energy Sale We invested in Gran Tierra Energy in June 2024 following the company’s exploration success in Ecuador. Immediately following our investment, Gran Tierra acquired i3 Energy in Canada. The transaction, which didn’t make financial or strategic sense, caused Gran Tierra’s stock to decline by over 40%. At Gran Tierra’s newly discounted share price, we decided to increase our ownership of and influence over the company. We ultimately bought 18% of the company and decided to join the board with the intention of improving Gran Tierra’s capital allocation decisions. Sensing the likely result of our decision, Gran Tierra’s board preemptively undertook a strategic review of its portfolio. That review resulted in a decision to sell the company’s Latin American business to surface value. That transaction, announced in early August of this year, enabled us to sell our position at an attractive price. Decision to Exit Seplat Energy We first started purchasing shares of Seplat Energy in March 2022. When the company bought Exxon out of Nigeria, we substantially increased our position. We always viewed Seplat as the best run Nigerian oil company. The company’s breakeven production costs were so low that Seplat was able to keep paying its dividend throughout 2020 when the Brent Crude oil price averaged $43 per barrel, including through the depths of the COVID-induced oil crash. And because of the Exxon deal, Seplat was able to more than double the business without raising equity. Despite these attractive attributes, Seplat traded at a substantial discount to international peers due to the poor reputation of its home country. Prior to 2026, the stock traded at a 20-30% free cash flow (FCF) yield and paid a high single-digit dividend yield, while also investing to grow production. We particularly liked Seplat’s shareholding structure. At the time of our investment, the company had a variety of unaffiliated shareholders, each with their own board representation. The French oil company Maurel et Prom owned 20% of Seplat; the two co-founders each owned stakes ranging from 6% to 12%; another 15% was owned by the South African asset managers Allan Gray and Sustainable Capital; and 14% of the company was owned by Monaco-based investor Samuel Dossou. In short, there was no single owner powerful enough to take advantage of minority investors and impair our investment. Early this year, the distributed ownership structure of Seplat ended abruptly. Tony Elumelu, a Nigerian billionaire, acquired Maurel et Prom’s 20% stake and was appointed to Seplat’s board. Shortly thereafter, the two South African asset managers sold their shares as well. Tony was the rumored buyer of their shares. While it was impossible for us to verify these rumors, it became clear to us that Tony had complete control over the company. We viewed Tony’s control with skepticism, but his purchase was viewed very favorably by local Nigerian investors. The local view was that finally Seplat has a ‘Big Man’ in charge who has the ear of the ‘Big Men’ in Abuja and can get things done. While there is probably truth to this, Tony’s corporate governance track record made us uncomfortable with his level of control. Once in control, Tony removed Roger Brown, Seplat’s foreign CEO whom we greatly respected, and installed a local Nigerian in his place. Tony also made himself the Chairman of Seplat’s board. Again, to our surprise, the market applauded these moves and the stock rallied further. We sold half our position on the day of the CEO change announcement and then met with both the new CEO and Tony himself to dig deeper into the new governance structure. After both meetings, and a subsequent further increase in the share price, we exited the position completely. We sold the last of our shares at a 10% FCF yield on our forward-year forecast, or a mid-teens FCF yield 3-5 years out. After we sold, the stock rallied another 15% and now trades at an estimated 8% FCF yield on forward estimates, and a low-teens FCF yield 3-5 years out. Seplat was a very successful investment for us. From when we purchased it to today, annual production and cash flow have more than tripled. Our Seplat investment returned approximately 250% prior to Tony's involvement, and more than doubled again in the short time after he bought in. In total, the position returned over 700% across our four-and-a-half-year holding period. Some part of this was good stock picking, and some part was luck. Brazil's Election Brazil’s election delivered a series of surprises: Flavio's first-round victory, Lula’s second-round victory, Justice Moraes' attempt to confiscate Flavio's passport, and Flavio's decision to relocate to the United States. With Lula still in power, we expect the Brazilian real will weaken as Lula forces policy rates lower without the necessary fiscal adjustment. This scenario will present a challenging macroeconomic backdrop for our companies but is not all bad news. In an environment of scarce capital, our well-capitalized portfolio companies will likely consolidate their sector leadership positions. Several of our Brazilian portfolio companies stand to benefit from softening competition from private equity. In the post-election sell-off, we added to our Brazilian currency hedge and our position in Grupo GPS. Grupo GPS is the leading business services outsourcing company in Brazil, and we recently profiled this relatively new investment as a case study of our process. If you haven’t already, we encourage you to watch our case study webinar ( access the replay via the following link : Grupo GPS Case Study - Oct 2026 - Video Replay ). Organizational Update In September, we added Will Robinson to our investment team. He joins us from Sixth Street Partners, where he was an associate on their Infrastructure investment team. Will originally hails from Texas, outside of Dallas, and received a B.B.A. in Finance from The University of Texas at Austin. We are excited for him to bolster the analytical horsepower of our mining research.
By Kieran Brennan • October 21, 2026
Grupo GPS - Case Study (Oct 2026) - Presentation + Q&A Replay
By Kieran Brennan • July 20, 2026
Dear Partners and Friends, PERFORMANCE Equinox Partners Precious Metals Fund, L.P. declined -6.0% in the second quarter of 2026, finishing the first half of the year up +1.3%. By comparison, in the second quarter, the price of gold declined -16.% and the MVIS Junior Gold Mining Index sold off -16.9%, finishing the first half of 2026 down -7.2% and -14.1% respectively. Performance for the quarter was driven by our exploration stage portfolio which in aggregate declined -9.3% amidst the declining gold price backdrop. Our portfolio of producing stage companies held up much better, only selling off -6.5%. Our largest producer, Solidcore Resources, was actually up +6% in the quarter. The portfolio also benefited from slightly elevated levels of cash, averaging 6% weight, which we were able to deploy part of as shares of our preferred companies returned back to our target IRR levels. Corporate Governance Corporate governance analysis is central to our research process. We view our long-term investments in publicly traded companies as partnerships with a company’s board of directors. Accordingly, we don't just want to know what decisions a board is making; we know why a board is making decisions. In our opinion, understanding a board’s motivation is the best way to gain durable insight into their corporate strategy and capital allocation policy. Our emphasis on corporate governance has helped us avoid value traps and understand our portfolio companies better. Active engagement is more than informed proxy voting. Active engagement entails a sincere dialogue with directors. While the relationships required for an honest back and forth are not easy to achieve, conversations with directors have become a real differentiator for our research process. Our corporate governance successes have added meaningful value, and our corporate governance failures have taught us important lessons. While each governance situation is unique, we face several recurring problems of note: Non-aligned directors: A surprising number of public company directors own little to no stock. These non-aligned directors fall into two categories: directors who lack sufficient wealth to own a meaningful amount of stock, and wealthy directors who choose not to own shares of the company that they govern. Both situations are problematic. Excessive executive option issuance: Ironically, the largest option grants tend to go to entrenched insiders that don’t need a payment to stay. As the interests of insiders and shareholders are clearly opposed in these cases, it is important that shareholders aggressively oppose excessive option issuance. Bundled voting: The sole purpose of bundling director elections is to reduce shareholder influence. The practice is gaining traction in Brazil, and we are actively opposing the trend. Stakeholder Capitalism: A theory typically used by boards to advance liberal environmental and social agendas that are at odds with shareholder interests. The resulting extreme ESG commitments can be both costly and morally objectionable. Poison Pill Adoption: While there are valid reasons to adopt a poison pill, most of the time they are used to further entrench management and boards and should be opposed by shareholders. Change of control payouts: An egregious practice of paying insiders an additional bonus to sell the company. Such payments are indefensible and the wrong way to address the problem of entrenched insiders. Corporate governance engagement is an art that goes well beyond the application of a set of rules. We don’t vote against every flawed director or proposal. Instead, we seek to explain to board members why we oppose certain practices and expect a good faith effort from them to address our concerns. We aim for improvements, not perfection. Corporate Governance Insights Applied The CEOs of Torex Gold Resources and B2Gold both announced their resignations in February of this year with gold trading north of $5,000 per ounce and gold mining equities indices hitting new highs. At both companies, the boards decided to promote the CFO to the open CEO role. In our opinion, these decisions reflect the boards’ intentions to prioritize the return of capital over growth strategies. Given the low valuations at which Torex and B2Gold currently trade, returning capital via share buybacks is especially accretive today. Accordingly, in both cases, the surprising leadership change made the companies more attractive investments, and we have been active buyers of both in recent months. Torex Gold Resources On February 4th, Jody Kuzenko, Torex’s CEO, announced her resignation. Given that Jody is 56 years old, the market was surprised by her unexpected departure, and Torex’s shares gapped down -12% on the news. If everything were fine, why would Jody leave the company she worked so hard to build over the previous decade? As long-term investors in Torex, we were in a great position to form our own opinion about Jody’s departure. Our conversations revealed two important things: First, Jody’s departure was a result of her sincere desire to take her career in a different direction and not the result of a problem at Torex. Secondly, Torex is going to generate an enormous amount of free cash flow, most of which will not be reinvested in mining activities, and Andrew Snowden, Torex’s CFO, is the right person to manage the capital return program. B2Gold On February 24th, Clive Johnson announced his resignation as the CEO of B2Gold. Given he was 73 years old, his retirement was not as surprising. Clive was a gifted CEO but not a fan of returning capital to shareholders through dividends or buybacks. Accordingly, his resignation drove B2Gold up 13% over two trading days. In our opinion, the stock market was rightly concerned that Clive would always push to build or buy another mine. Clive’s departure and the elevation of Mike Cinnamond, the CFO, provides clarity on B2Gold’s capital allocation framework going forward. The company is clearly focused on “per-share” value creation, which has resulted in increased share buybacks and dividends. Conclusion In both cases, the boards of Torex and B2Gold are prioritizing shareholder value over the “growth at any cost” mentality that has plagued the mining sector for decades. Our corporate governance engagement with these two companies provided us with a front-row seat to this important change that has not been fully appreciated by the market. Organizational Update In May, we added Roman Fuzaylov to our investment team. Roman has 20 years of experience as an investor across frontier and emerging markets. He started his career as a junior analyst at Prince Street Capital in 2006 and eventually became a partner and portfolio manager of their Tamerlane Fund, a regional mandate focused on Emerging Europe, Middle East and Africa. More recently, he was a co-portfolio manager of the Helios Seven Rivers Fund, a joint venture with Helios Investment Partners that focused on public markets investing across the African continent. Roman originally hails from Uzbekistan, is fluent in Russian, and is very well aligned with our long-term, fundamental approach to investing. In April, we hired Luca Grandinetti as a junior operations analyst. In addition to providing versatile support across our operations and middle-office functions, Luca has been instrumental in our Firm-wide efforts to centralize and organize the data around portfolio company corporate governance during proxy season. Prior to joining us, Luca worked at the Mitsui Group and Mirador, Inc.
By Kieran Brennan • July 20, 2026
Dear Partners and Friends, PERFORMANCE Equinox Partners, L.P. declined (-12.4%) net of fees in the second quarter of 2026, finishing the first half of the year up +15.8%. During the second quarter, the S&P 500 index appreciated +15.2% and is up +10.2% through the first half of the year. Equinox’s poor performance for the quarter was driven by declines in both our mining and energy equities. Corporate Governance Corporate governance analysis is central to our research process. We view our long-term investments in publicly traded companies as partnerships with a company’s board of directors. Accordingly, we don't just want to know what decisions a board is making; we know why a board is making decisions. In our opinion, understanding a board’s motivation is the best way to gain durable insight into their corporate strategy and capital allocation policy. Our emphasis on corporate governance has helped us avoid value traps and understand our portfolio companies better. Active engagement is more than informed proxy voting. Active engagement entails a sincere dialogue with directors. While the relationships required for an honest back and forth are not easy to achieve, conversations with directors have become a real differentiator for our research process. Our corporate governance successes have added meaningful value, and our corporate governance failures have taught us important lessons. While each governance situation is unique, we face several recurring problems of note: Non-aligned directors: A surprising number of public company directors own little to no stock. These non-aligned directors fall into two categories: directors who lack sufficient wealth to own a meaningful amount of stock, and wealthy directors who choose not to own shares of the company that they govern. Both situations are problematic. Excessive executive option issuance: Ironically, the largest option grants tend to go to entrenched insiders that don’t need a payment to stay. As the interests of insiders and shareholders are clearly opposed in these cases, it is important that shareholders aggressively oppose excessive option issuance. Bundled voting: The sole purpose of bundling director elections is to reduce shareholder influence. The practice is gaining traction in Brazil, and we are actively opposing the trend. Stakeholder Capitalism: A theory typically used by boards to advance liberal environmental and social agendas that are at odds with shareholder interests. The resulting extreme ESG commitments can be both costly and morally objectionable. Poison Pill Adoption: While there are valid reasons to adopt a poison pill, most of the time they are used to further entrench management and boards and should be opposed by shareholders. Change of control payouts: An egregious practice of paying insiders an additional bonus to sell the company. Such payments are indefensible and the wrong way to address the problem of entrenched insiders. Corporate governance engagement is an art that goes well beyond the application of a set of rules. We don’t vote against every flawed director or proposal. Instead, we seek to explain to board members why we oppose certain practices and expect a good faith effort from them to address our concerns. We aim for improvements, not perfection. OPEC's Last Stand The Equinox Partners upstream oil investments are great at $80 oil, good at $70 oil and reasonable at $60 oil. The 40% portfolio weighting in oil equities reflects our conviction that oil prices will be closer to $80 than $60. Our view incorporates the natural oil supply-demand balance as well as our confidence that this supply demand balance is not solely determined by market forces. Chief amongst those non-market forces is OPEC, an organization that we believe will fight to stay relevant. OPEC’s operating premise is that small changes in oil supply drive much larger changes in the oil price. Therefore, oil exporting countries should modestly restrict oil supply to maximize their revenues. China and America’s active management of the oil market in recent years poses a serious challenge to OPEC’s influence. Having successfully suppressed the oil price with a series of market interventions, America and China have no intention of retreating to a passive approach and hoping for the best. OPEC now faces a stark choice: prevent America and China from rebuilding their oil inventories or become irrelevant. Coordinated interventions intended to manage down the price of oil are nothing new. Oil importing countries launched the International Energy Agency (IEA) in 1974 to do exactly this in the wake of the 1972-1973 Arab oil embargo. Since then, the IEA has formally coordinated oil importing countries’ response to oil market disruptions and OPEC’s oil price manipulation. IEA members, like OPEC members, make certain commitments. Specifically, IEA member countries must maintain 90 days of oil inventory and have a demand restraint program capable of reducing national oil consumption by up to 10%. These commitments enable the IEA to coordinate inventory releases and suppress demand during a crisis such as an oil embargo or war in the Persian Gulf. Absent a crisis, the IEA relies on soft power to contain oil prices. The organization promotes oil alternatives, warns about climate change, and makes pessimistic projections about future oil demand. The IEA has not, however, coordinated direct oil price suppression as a regular course of business. During his first term, Trump followed the historic norms for IEA member countries. When he wanted the oil price down in 2018, he turned to OPEC, not the IEA. Trump famously telephoned Saudi’s crown prince, MBS, asking him to produce more oil. We don’t know exactly what concessions Saudi’s crown prince secured in exchange for the additional oil supply but, presumably, Saudi assistance came at some cost. The Biden administration, perhaps because of its poor relationship with Saudi Arabia, took a more aggressive approach to the oil market, and released 50 million barrels from America’s Strategic Petroleum Reserve in 2021. Biden didn’t seek Congressional authorization for this release, claiming he was just swapping current barrels for future ones. A sleight of hand for sure, but one that recognized America’s new status as a net oil exporter. After Russia invaded Ukraine, Biden was free to take additional measures. He declared an emergency and released an additional 180 million barrels from America’s Strategic Petroleum Reserve, promising to eventually replenish the oil stockpiles he sold, which he only partially did. Once Biden proved that oil price could be influenced through active inventory management, his strategy was certain to be copied. The Iran war offered America and China an opportunity to do exactly that. The US and China have released hundreds of millions of barrels of oil and refined product into the market since the start of the war with Iran. Beyond inventory sales, Trump has constantly talked down the oil price, promised a plunge in oil prices when the war ends, and encouraged additional oil production from Venezuela. The Chinese have taken even bolder action, cutting their domestic demand by millions of barrels a day. While it is impossible to know how much of the Chinese demand reduction is actual demand suppression and how much of it is Chinese inventory sales, the estimated 3-5 million barrel a day decrease in Chinese oil demand since the Iran war started has helped keep a lid on oil prices. While there is no formal coordination between the US and China, the shared interest is clear. Both countries are highly indebted and want low oil prices to contain inflation expectations and domestic interest rates. Combined, the US and China have $45 trillion in federal government debt and another $80+ trillion in private sector debt. A little oil price manipulation probably seems like a small price to pay for the lower financing cost of debt. Low oil prices also serve America and China’s geopolitical interest vis-a-vis Russia. From the US perspective, low oil prices make Russia more likely to do a deal in Ukraine. From the Chinese perspective, low oil prices make Russia more dependent on China. In both cases, American and China clearly believe their geopolitical interests are served by lower oil prices. OPEC has long worried that large oil inventories in oil importing countries could be used to blunt OPEC’s influence over the oil price. America and China’s actions confirm that fear. OPEC is losing members, losing power, and now has a very difficult task ahead: if OPEC wants to stay relevant, OPEC must prevent America and China from restocking their inventories when the straits of Hormuz reopen. This will require carefully managed OPEC oil production and tough conversations with China and America. If OPEC succeeds in reasserting their position in the oil market, the oil market won’t get the full benefit of short-term oil restocking in the US and China. But, longer-term, OPEC’s relevance should ensure oil prices of at least $80. If, on the other hand, OPEC doesn’t reassert itself, China and America will restock their oil inventories quickly, which is short-term oil bullish. Then, China and America will use their excess oil inventories to manage down the oil price, which is long-term bearish.
By Kieran Brennan • July 15, 2026
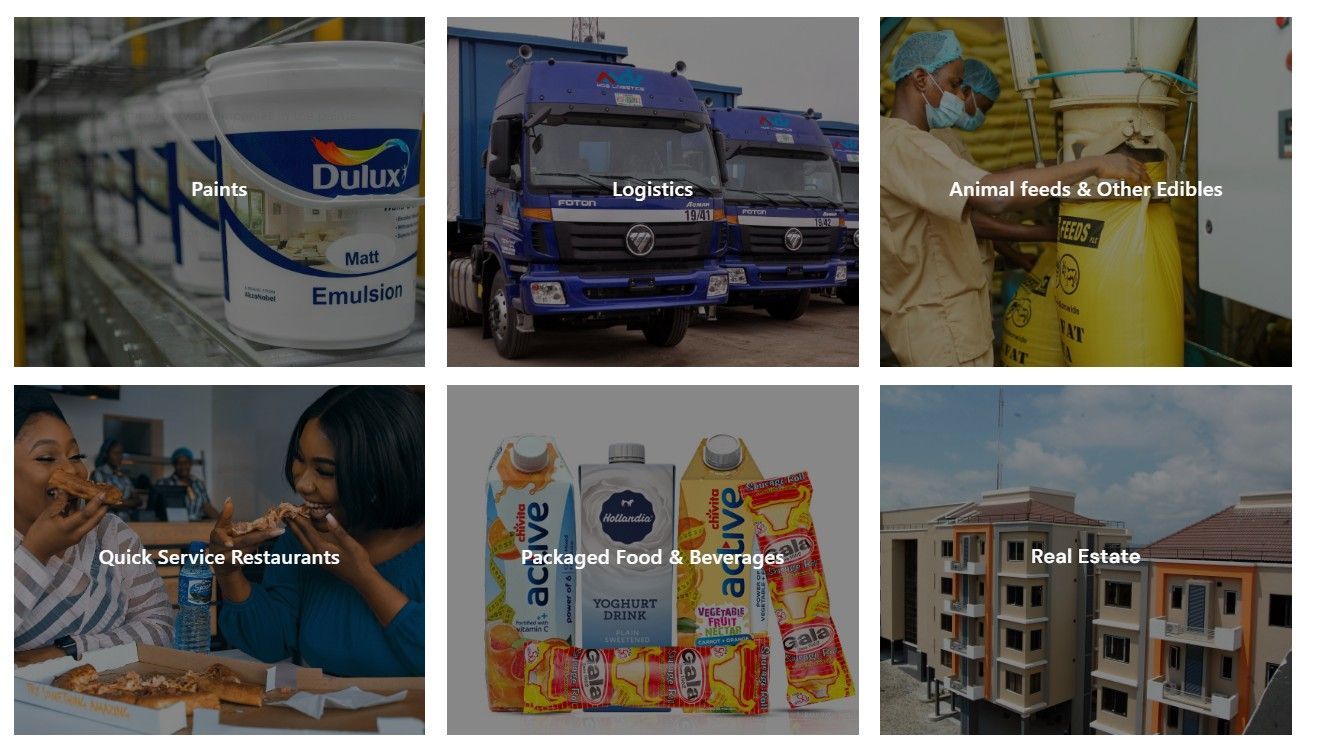
Dear Partners and Friends, PERFORMANCE Kuroto Fund was up +3.5%, net of all fees, in the second quarter of 2026, and finished the first half of 2026 up +32.0%. By comparison, the MSCI Emerging Markets Index returned +24.2% in the quarter and finished up +24.0% for the first half of the year. The MSCI Frontier Markets Index was up +11.2% in the second quarter and up +10.2% for the first half of 2026. Performance in the second quarter was led by strong returns of Guaranty Trust, MTN Ghana, and UAC Nigeria, the last of which we will discuss in greater detail in this letter. These significant gains in our largest African equity holdings were partially offset by the pullback in several of our energy sector holdings. Our portfolio also suffered from the continued sell-off in the Brazilian equity market. We are using this weakness as an opportunity to deploy capital countercyclically into a handful of world-class businesses. Revisiting UAC Nigeria We recently returned from a trip to Nigeria and Ghana where we visited the management teams of several of Kuroto Fund’s long-term investments. One of those investments, United Africa Company of Nigeria (UACN), has appreciated significantly, entering the top 5 by position size for the first time. Given the meaningful contribution to return and large position size, we thought it would be timely to review the investment and learnings from our latest site visit. In the 1920s and 1930s, Lever Brothers Limited established the United Africa Company to facilitate trade in the region, mainly supplying palm oil for their soap operations. In 1974, the Nigerian subsidiary UACN became one of the first publicly listed stocks in the country. Today, it is one of the premier Nigerian companies with an iconic headquarters in Lagos. In the 1990s, Lever Brothers Limited, now known as Unilever, fully exited its shares and UACN diversified into several unrelated businesses, including property development, snack foods (sausage rolls and ice cream), paint, animal feeds, restaurants, and logistics.
More Posts